From Cash to Compliant: The Formalization Wave Reshaping Asia-Pacific's Small Business Economy — and the US Service Firms Profiting From It
The Quiet Revolution Beneath Asia-Pacific's Headline Numbers
When US business executives think about Asia-Pacific commercial opportunity, they tend to think in large denominators: GDP growth rates, urban consumer populations, foreign direct investment flows. These are legitimate frames. They are also, in many cases, measures of the formal economy — the layer of economic activity that is captured in official statistics, registered with tax authorities, and visible to international investors.
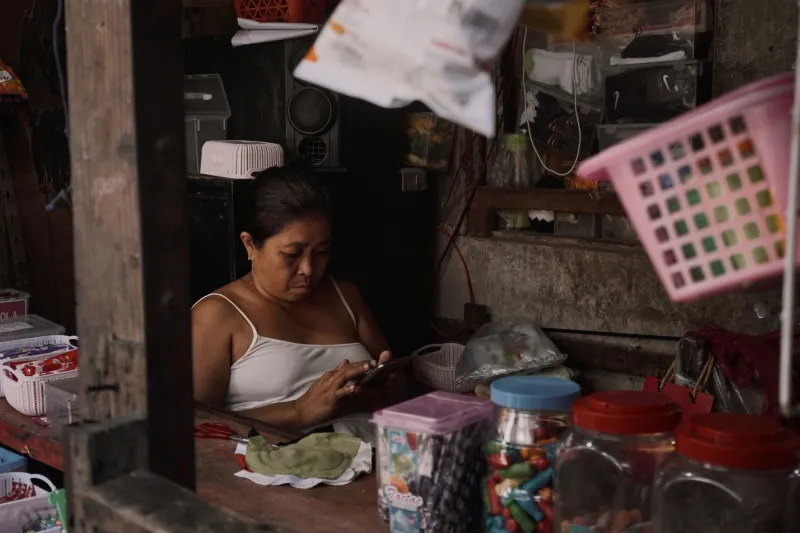
Below that layer sits a parallel economy of extraordinary scale. The International Labour Organization estimates that informal employment accounts for more than 60% of total employment across Southeast Asia. In countries like Indonesia, the Philippines, and Vietnam, informal micro and small enterprises represent the dominant mode of economic organization for hundreds of millions of working people. These are not marginal actors. They are the structural foundation of the regional economy.
What is changing — with significant speed and with direct commercial implications for US service firms — is the rate at which these enterprises are transitioning out of informality. The drivers of this transition are multiple and reinforcing, and they are creating demand for services that US companies are well-positioned to deliver.
What Is Driving Formalization — and Why It Is Accelerating Now
Three structural forces are converging to push Asia-Pacific's informal sector toward formal participation at a pace that would have seemed implausible a decade ago.
Digital payment infrastructure. The penetration of mobile payment platforms across Southeast Asia has been dramatic. GoPay and DANA in Indonesia, GCash in the Philippines, PromptPay in Thailand, and VietQR in Vietnam have brought digital transaction capability to populations that previously had no banking relationship at all. When a street vendor or small workshop operator begins transacting digitally, they leave a data trail. That data trail becomes the basis for credit assessment, tax identification, and regulatory visibility in ways that cash transactions never enabled. Formalization frequently begins not with a deliberate regulatory choice but with the practical adoption of digital payment tools.
Supply chain qualification requirements. As global brands and regional manufacturers tighten their supplier qualification standards — driven by ESG reporting requirements, import compliance demands from major US and European buyers, and post-pandemic supply chain resilience priorities — they are imposing formal documentation requirements on their supplier bases. A small garment workshop or food processing facility that previously operated without formal registration must now produce tax compliance certificates, employee registration records, and environmental compliance documentation to retain its position in a commercial supply chain. The qualification requirement is the formalization trigger.
Government revenue imperatives. Across the region, governments that expanded fiscal spending during the pandemic period are now prioritizing domestic revenue mobilization. Tax authority digitization programs — Indonesia's Coretax system, Vietnam's electronic invoice mandate, the Philippines' expanded BIR digital infrastructure — are making it progressively harder for small enterprises to remain invisible to revenue authorities. The compliance cost of informality is rising.
The Commercial Opportunity This Creates for US Service Firms
Formalization at scale generates demand across a predictable set of service categories. US companies operating in the following verticals have credible, scalable opportunities in this transition.
Accounting and compliance software. The millions of small enterprises entering formal tax and regulatory systems need tools to manage that compliance. US software companies with adaptable SME accounting platforms — particularly those with API connectivity to local tax authority systems — have a substantial addressable market. The key commercial challenge is localization: platforms must integrate with country-specific tax codes, invoice formats, and regulatory reporting structures. Companies that have invested in genuine localization rather than surface-level translation are finding strong adoption curves.
Embedded fintech and working capital solutions. Newly formalized enterprises with transaction histories but limited credit records represent an underserved lending market. US fintech firms and alternative lending platforms that can use digital transaction data as a credit proxy — rather than requiring traditional collateral or formal financial statements — are capturing a market segment that conventional banking has historically ignored. Several US-backed platforms operating in Indonesia and the Philippines have demonstrated that default rates in this segment, when underwritten with transaction data, are commercially manageable.
Business process outsourcing and advisory. Small enterprises moving from informal to formal operations frequently lack the internal capability to manage compliance, payroll, HR administration, and regulatory reporting. US BPO and professional services firms that can deliver these functions at price points appropriate for SME clients — through technology-enabled delivery models rather than traditional consulting structures — are building recurring revenue relationships with a client base that is growing by regulatory design.
Supply chain traceability and certification services. For small producers entering formal supply chains, the documentation requirements imposed by global buyers create demand for traceability software, third-party audit services, and certification support. US companies in this space — particularly those with experience in food safety, textile supply chain documentation, and environmental compliance — have a direct commercial application in markets where supplier formalization is being driven by export qualification requirements.
Overlooked Verticals Worth Examining
Beyond the obvious fintech and accounting software categories, several less-examined verticals are generating notable commercial activity.
The halal certification and compliance sector in Indonesia and Malaysia presents a specific formalization dynamic: small food producers seeking access to formal retail channels must obtain halal certification through processes that are increasingly digitized and compliance-intensive. US firms with food safety compliance expertise have found credible entry points here.
Agricultural input and output traceability in Vietnam, Thailand, and the Philippines is generating demand for farm management software and cooperative digitization services as smallholder farmers enter formal supply chains serving international food companies with strict provenance documentation requirements.
Health and safety compliance training for small manufacturers entering formal export supply chains is an underdeveloped service category with consistent demand driven by buyer qualification requirements.
Building a Scalable Model
The commercial challenge in serving Asia-Pacific's formalizing informal sector is unit economics. Individual small enterprises have limited service budgets. Scalable business models in this space share a common structural feature: they deliver value through technology platforms rather than labor-intensive service delivery, and they acquire customers through channel partnerships — with banks, mobile payment platforms, industry associations, and government formalization programs — rather than direct sales.
US companies that have succeeded in this space have treated channel partnership development as their primary go-to-market investment. The distribution infrastructure already exists, built by the mobile payment platforms and digital banking providers that first established relationships with these enterprises. The commercial opportunity lies in layering complementary services onto that existing infrastructure.
The formalization of Asia-Pacific's informal economy is not a peripheral story. It is the structural transformation of the region's largest economic sector — and it is generating demand for exactly the services that US business and technology firms are built to provide.