Closing Windows: How Asia-Pacific's Green Energy Policy Wave Is Leaving US Companies Behind
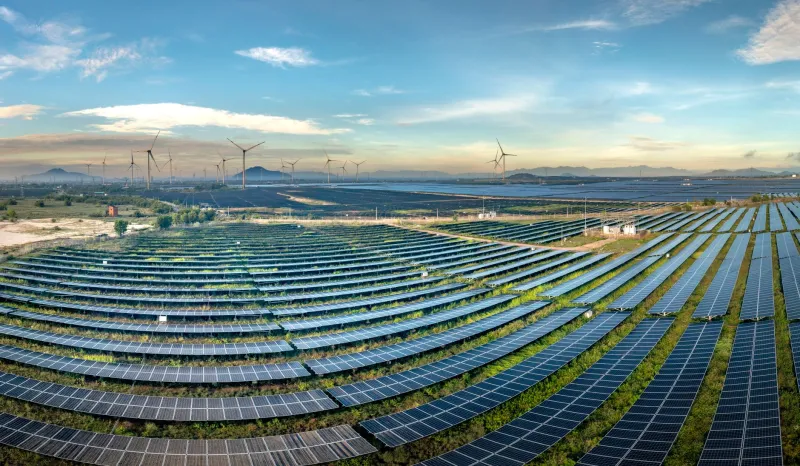
A Policy Shift That Has Moved Faster Than US Commercial Strategy
For much of the past decade, US companies observing Asia-Pacific's energy transition narrative could reasonably treat it as a long-horizon story. Targets were ambitious but enforcement was uneven. Regulatory frameworks were aspirational. The investment cycle seemed to allow for a measured, wait-and-see approach.
That calculus has changed materially. Across the region's major economies, the shift from voluntary energy transition commitments to mandatory compliance structures — with procurement targets, grid integration deadlines, and carbon pricing mechanisms — has accelerated significantly since 2022. What was once a policy conversation is now a procurement reality. And US companies that positioned themselves as patient observers are finding that the seats at the table are being filled by European, Japanese, South Korean, and increasingly Chinese clean technology providers who arrived earlier and built relationships when the cost of entry was lower.
This is not a story about US companies being uncompetitive. It is a story about timing — and the specific commercial windows that open and close as governments move through distinct phases of energy transition policy implementation.
Country-Level Timelines and the Urgency They Create
The Asia-Pacific energy transition is not a single market event. It is a series of country-specific policy cycles, each with its own regulatory architecture, procurement structure, and commercial opportunity profile. Understanding where each major market sits in that cycle is the starting point for any credible commercial strategy.
Vietnam is currently navigating the implementation of its Power Development Plan 8, which targets 50% renewable energy in the national grid mix by 2030. After a turbulent period of feed-in tariff policy reversals, the government has moved toward a competitive auction framework. The window for early positioning in the advisory, engineering, and project finance services sectors around this buildout is open now — but the primary contracts for the largest installations are being structured in the near term. US firms in energy consulting, grid management software, and project risk management have a credible entry point, but the timeline for first-mover positioning is measured in quarters, not years.
India has committed to 500 gigawatts of non-fossil fuel capacity by 2030, a target that requires roughly $300 billion in investment over the remainder of the decade. The Production-Linked Incentive scheme for solar manufacturing has already attracted significant domestic and foreign capital. For US companies in clean tech components, storage technology, and grid infrastructure services, the opportunity is substantial — but the regulatory preference for domestic manufacturing content is increasing, making early local partnership establishment a commercial necessity rather than an option.
Japan, following its revised Green Transformation strategy, is deploying significant capital into offshore wind, hydrogen, and ammonia co-firing infrastructure. The procurement cycles for major offshore wind projects in Japanese territorial waters are now active, and the technical partnership requirements embedded in those procurement structures favor companies with demonstrated project histories. US firms that have not yet established relationships with Japanese utilities and engineering companies are entering a procurement environment where relationship tenure already matters.
Australia's Capacity Investment Scheme and the associated state-level renewable energy zone frameworks are creating procurement activity across battery storage, transmission infrastructure, and grid-scale solar that has attracted significant international interest. Notably, Australia's regulatory environment is among the most accessible in the region for US companies, making it a viable first-entry point for firms building Asia-Pacific clean energy credentials.
The Philippines and Indonesia represent the largest emerging opportunity frontiers, with both countries facing enormous infrastructure deficits and active international financing from multilateral development banks. Entry costs remain lower here than in more mature markets, but regulatory complexity and local partnership requirements demand careful navigation.
The ESG Supply Chain Dimension
Beyond direct energy infrastructure, the region's green policy shift is reshaping supply chain qualification standards in ways that create commercial pressure on US companies as buyers, sellers, and service providers simultaneously.
Major Asia-Pacific manufacturers serving US retail and technology brands are increasingly subject to Scope 3 emissions reporting requirements imposed by their largest customers. This is generating demand for carbon accounting services, renewable energy procurement advisory, and ESG supply chain audit capabilities that US business services firms are well-positioned to provide — but only if they have built regional delivery capacity.
The commercial logic here runs in both directions. US companies that can help Asia-Pacific suppliers meet the ESG qualification standards required by US importers are solving a real and growing problem. The firms building that capability now are establishing commercial relationships that will compound in value as compliance requirements tighten.
What US Companies Need to Do Differently
The companies gaining ground in Asia-Pacific's energy transition markets share several structural characteristics that distinguish them from those still observing from the sidelines.
First, they have made local partnership establishment a priority rather than a deferred step. In every major Asia-Pacific clean energy market, the regulatory environment rewards local content, local knowledge, and local relationships. US companies that arrive with a fully formed product or service but no regional commercial infrastructure are at a structural disadvantage relative to competitors who have spent two or three years building those foundations.
Second, they treat regulatory monitoring as a commercial intelligence function rather than a compliance overhead. Policy timelines in this space change. Feed-in tariff structures are revised. Procurement rules shift. Companies with active regulatory intelligence capabilities respond faster to these changes and capture the commercial opportunities that transitions create.
Third, they have made the internal investment case for Asia-Pacific clean energy exposure on a market-specific basis rather than treating the region as a single opportunity. The risk profiles, entry costs, and commercial timelines in Vietnam, India, Japan, and Australia are meaningfully different. Strategies calibrated to that specificity outperform those built on regional generalization.
The energy transition across Asia-Pacific is not a trend that is approaching. It is a policy and commercial reality that is already in motion. The question for US companies is not whether to engage — it is whether they engage while there is still first-mover value available, or after the initial positions have already been established.